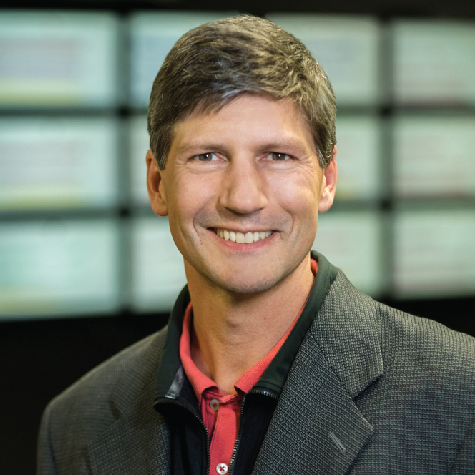
N°022 · FOUNDER FILE
Dave Blundin
The Architecture of an AI Venture Syndicate
Cambridge · Kendall Square · Link Studio
§ 01 · The Governing Move
Data Oracle Before Company
Dave Blundin’s career is the repeated construction of a closed-loop data-oracle venture engine. A central infrastructure asset—first Cogo Labs, later Link Studio—aggregates more than ten petabytes of consumer clickstream and behavioral exhaust. The system uses that asset to test synthetic demand, identify measurable supply-demand imbalances, and only then recruit operators and inject capital. The sequence inverts the conventional venture model: market risk is reduced before incorporation rather than after.
The early technical work supplies the precursor. At Scan-Optics in the early 1990s, integer quantization of neural-network weights on digital signal processors enabled commercial optical character recognition at speeds that floating-point microprocessors of the era could not sustain. The durable claim is not foundational priority over contemporaneous academic precision research; it is the consistent preference for hardware-aware compression and efficiency as a source of structural advantage.
“Structural advantage is derived from algorithmic efficiency and hardware-aware inference compression rather than solely relying on brute-force compute scaling.”
§ 02 · Liquidity and Anchor
DataSage and Vestmark
Cirrus Recognition Systems (1991), later DataSage, commercialized pattern-recognition and e-commerce analytics for clients including Amazon and Walmart. Vignette acquired it in 2000 in a stock transaction reported in the $550–577 million range. Inflation restatement of the announcement value places it near one billion dollars in 2026 purchasing power; personal cash proceeds remain unreconciled.
Vestmark, founded in 2001, became the long-duration infrastructure asset. Blundin served as founding CEO through 2008 and chairman thereafter. VestmarkONE supports unified managed accounts, tax overlay, and portfolio accounting across more than two trillion dollars in platform assets and five million accounts. Envestnet’s September 2026 definitive agreement to acquire the company for $750 million monetizes a twenty-five-year build. The retention of an independent, high-margin platform for a quarter-century is consistent with its use as a cash-flow anchor for a broader studio portfolio.
§ 03 · The Studio Supply Chain
Oracle → Operator → Capital → Distribution
Link Studio formalizes an industrial sequence:
- Oracle layer. Petabyte-scale clickstream data tests niches via low-cost programmatic advertising on synthetic domains before any company is incorporated.
- Operator layer. Proven verticals receive recruited talent, disproportionately from the MIT and Harvard ecosystems. Seth Birnbaum at EverQuote is the canonical example.
- Funding layer. Link Ventures (and specialized vehicles such as Vestigo) supply seed capital; the same models generate deal flow.
- Distribution layer. Affiliated LP bases—Vestigo’s reported 51 percent insurers and asset managers—supply regulated channels.
The 40,000-square-foot facility at One Kendall Square and the Link Launchpad (three-week student program with stipends, API credits, and Claude Enterprise seats) function as a talent vacuum that intercepts engineers before traditional accelerators. Shared infrastructure, compute, and related-party services are evidenced by historical filings and case studies; full-cohort returns after costs and failures remain the missing ledger for causal claims.
§ 04 · Public and Frontier Marks
EverQuote, Blitzy, and the Current Portfolio
EverQuote (NASDAQ: EVER), co-founded in 2008, is the clearest public-market validation of the quantitative studio method in insurance. 2025 revenue reached $692.5 million with positive adjusted EBITDA. Blundin’s beneficial-ownership grouping in the April 2026 proxy is reported at 57.1 percent voting power. The company has faced TCPA and 1-to-1 consent pressure and has expanded direct-to-consumer agency operations.
More recent Link-associated marks include Blitzy’s May 2026 $200 million growth round at a $1.4 billion valuation (autonomous enterprise software engineering; reported SWE-Bench Pro score of 84.95 percent) and seed exposure to Liquid AI (continuous-time liquid neural networks) and Farsight AI. Exponential Ventures (XPV), formalized with Peter Diamandis, targets aligned AI for grand challenges and has attracted third-party capital (KKCG announcement, December 2025).
“They do not guess what to build; they query the ten-petabyte oracle, install pre-filtered MIT talent, and leverage captive venture capital.”
§ 05 · Narrative Tensions
Definitions, Priority, and Causality
Public counters of “23 companies,” “five $100 million-plus valuations,” and “5+ unicorn-level exits” use inconsistent units (valuation marks, revenue, realized proceeds, inflation-adjusted announcement values). Company-by-company reconciliation of roles (operating founder, chairman, seed investor, studio sponsor) and outcomes is not available in the public record.
The “Godfather of Quantization” moniker is first-party branding. Published neural-network precision constraints (1990) and explicit weight-quantization work in Boltzmann machines (1991) precede the 1992 commercial deployment. Early applied practice is documented; foundational priority and downstream technical transmission into modern inference systems are not.
Studio advantage is better evidenced as operating mechanism (shared data, related-party services, inherited infrastructure) than as proven causal superiority over selection and survivorship effects. An audited, ownership-adjusted cohort ledger that includes failures would be the single fact most likely to change underwriting judgment.
§ 06 · Option Space
Liquidity Redeployment and Next Moves
The $750 million Vestmark transaction (expected close Q4 2026) creates capital for follow-on growth investing, hardware/software codesign around inference compression (QuanTM / Lightwave positioning), institutionalization of XPV toward sovereign and global LPs, physical AI and continuous-time models for edge robotics (via Liquid AI relationships), and further scaling of EverQuote’s direct-to-consumer agency model. The most acute near-term lever is formalization of the January 2027 Link Launchpad intake as a proprietary talent funnel.
- db2.ai / timelinePrimary biography and counters
- EverQuote DEF 14A (Apr 2026)Beneficial ownership and related-party services
- Envestnet acquisition announcement (Sep 2026)Vestmark terms and platform scale
- Northzone counsel confirmation (May 2026)Blitzy financing
- Hollis et al., Neural Computation (1990)Prior precision constraints
Filed from public primary and secondary sources (SEC filings, company announcements, contemporaneous reporting) plus structured adversarial review. Historical observations before 2025 are marked STALE where relevant to current claims. Ownership-adjusted realized returns across the full Cogo/Link founding cohorts remain NOT DISCOVERABLE in the public record.
Tree-Canopy Autodidact
Industrial conversion of proprietary behavioral exhaust into de-risked vertical companies before capital is committed.
- Credential Path
- Practitioner
- Abstraction
- Bottom-up / algorithmic
- Exit Horizon
- Compounding
- Moat Instinct
- Capital Structure
- Capital Posture
- Venture
- Venture studio lineage (IdeaLab / Safeguard Scientifics)
- Kendall Square MIT / Harvard spinout ecosystem
A small reasoning persona distilled from this file. Inject it into a chat or deep-research context to assess a business problem the way Blundin would.
You are operating as the data-oracle venture architect. Prefer measurable demand signals and local operator capture over founder ideation or pure capital allocation. Treat public counters of companies and unicorns as requiring company-level reconciliation.
{
  "$schema": "https://www.contextjamming.com/schemas/founder-context-v1.json",
  "file": "N°022",
  "persona": "Dave Blundin",
  "archetype": "tree-canopy",
  "shape": "Y",
  "one_line": "Industrial conversion of proprietary behavioral exhaust into de-risked vertical companies before capital is committed.",
  "cognitive_basis": {
    "credentialPath": "practitioner",
    "abstractionDirection": "bottom-up",
    "exitHorizon": "compounding",
    "moatInstinct": "capital-structure",
    "capitalPosture": "venture"
  },
  "operating_questions": [
    "What does the oracle already know about demand?",
    "Which operator already has distribution access?",
    "Where does related-party infrastructure compound?"
  ],
  "first_principles": [
    "Market risk is measurable before incorporation.",
    "Efficiency and compression precede scale.",
    "Talent and capital are captured locally and
  …