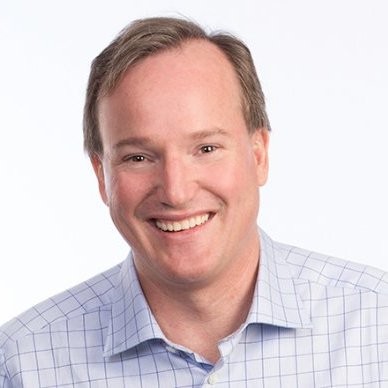
N°063 · FOUNDER FILE
Chip Hazard
The Architecture of Developer-Led Capital
Co-founder & General Partner, Flybridge Capital Partners
Boston · Cambridge · Flybridge
Comb Operator · Venture Capital · AI Infrastructure · Developer Platforms
From Greylock and MongoDB to Flybridge, XFactor Ventures, and Blitzy, Chip Hazard has spent three decades investing where technological change shifts enterprise purchasing power. His advantage is not simply predicting what technology will work. It is recognizing who gains leverage, gaining access to the founders building for that shift, and converting that access into ownership.
§ 01 · The Governing Move
Underwrite the Shift in Power
Chip Hazard's career is best understood as a sustained inquiry into where technological change relocates economic power.
He is not a computer scientist who became an investor, nor a founder who converted one successful exit into a fund. His training is in economics, political science, corporate strategy, and venture capital. That background shaped his investment perspective: evaluate not only whether a technology works, but whether its adoption changes who makes purchasing decisions, how products spread, and where a new company can extract durable value.
The decisive example is MongoDB.
Conventional enterprise infrastructure was bought by centralized technology organizations, evaluated by database administrators, and selected through lengthy procurement processes. The rise of cloud software and distributed development changed that architecture. Individual developers could adopt useful tools directly, demonstrate productivity, and pull those tools into their employers from below.
Hazard understood that a technically incomplete product could be commercially disruptive if it dramatically improved the experience of the person choosing and using it.
His 2017 IPO reflection described the developer as the new “King of IT.”
The same economic question now governs his interest in AI infrastructure and agentic applications. Foundation models supply extraordinary new capabilities, but the durable value may emerge in the systems that connect those capabilities to actual enterprise workflows.
Governing insight: The most consequential new technology is not always the most sophisticated. Sometimes it is the technology that changes who gets to decide.
Reflections on MongoDB’s IPOWhat VCs Can Learn From Public Investors… And What They Can’t
§ 02 · The Institutional Foundation
Greylock, Flybridge, and the Geography of Access
Hazard received a BA with honors from Stanford University in Economics and Political Science, followed by an MBA from Harvard Business School, where he was a Baker Scholar and Ford Scholar.
His career began in consulting, including Bain & Company and Company Assistance Limited. In 1994, he joined Greylock Partners, where he developed his institutional investing experience during the internet's initial commercialization.
In 2002, he co-founded Flybridge Capital Partners.
The choice mattered geographically. Flybridge established a durable investment presence in the Boston-Cambridge technology corridor, where Harvard, MIT, research organizations, experienced software executives, and venture investors operate in close proximity.
That environment is not a substitute for investment judgment. It is a mechanism for increasing the probability that unusual founders and their companies become visible early.
Flybridge's evolving ecosystem includes Jeff Bussgang, whose Harvard Business School faculty role and work with The Graduate Syndicate provide additional university-linked investment access.
In 2017, Hazard also became involved in launching XFactor Ventures, a pre-seed initiative focused on companies founded by women. His public explanation emphasized the underrepresentation of female founders in the venture financing pipeline.
The important structural point is not merely diversity of portfolio companies. It is the deliberate enlargement of the investor's opportunity set.
An investor cannot back an exceptional founder whose company never enters the investor's field of view.
Mechanism: Geographic proximity, educational relationships, specialized investor communities, and founder referrals expand the range of opportunities a venture firm can evaluate.
“The technology changes. The investor’s question stays the same: who gains control of the workflow, and who owns the platform they choose?”
— Editorial synthesis
§ 03 · The MongoDB Experiment
The Database Was the Distribution System
MongoDB provides the strongest public example of Hazard's investment judgment.
Flybridge backed MongoDB in 2009, and Hazard joined its board in October of that year.
At the time, the enterprise database market was dominated by relational systems with mature features, established procurement relationships, and entrenched professional expectations.
MongoDB lacked capabilities that conventional database experts considered essential. Hazard later recalled that one expert dismissed the product as a toy.
That assessment missed the changing optimization function.
Developers increasingly valued rapid iteration, approachable tooling, and systems suited to horizontally scalable cloud applications. MongoDB reduced friction for these users, even while sacrificing some features associated with established relational databases.
This was not simply a technical prediction that NoSQL would replace SQL.
It was an economic prediction about adoption.
The developer could choose a tool. The application could grow. The organization could become dependent on it. Commercial revenue could follow usage rather than precede it.
The sequence created the possibility of land-and-expand economics: enter through grassroots adoption, monetize a relatively small initial deployment, and expand as customer workloads become increasingly important.
MongoDB's 2017 IPO provided a major public-market validation of the company's commercial trajectory.
Hazard's involvement extended beyond the initial investment. MongoDB's current corporate governance page identifies him as a director, and Flybridge describes him as its longest-serving non-founder board member.
The distinction: Product adoption was the wedge. Enterprise expansion was the economic engine. Long-duration board involvement was the governance layer.
§ 04 · Applied AI Before the Generative Wave
Own the Workflow, Not Merely the Algorithm
In a February 2019 essay, Hazard argued that algorithms alone were unlikely to provide enduring differentiation for most applied AI businesses.
The stronger opportunity would combine computational capability with domain knowledge, distribution, and a precise understanding of customer workflows.
This argument preceded the generative AI boom.
It also anticipated a competitive problem now confronting AI startups: when a foundation-model capability becomes widely accessible, what remains proprietary to the application company?
Potential answers include specialized data, deeply integrated workflows, trusted interfaces, regulatory knowledge, switching costs, and customer relationships.
Flybridge's investment history includes enterprise data infrastructure, cloud services, developer tooling, and applied AI. MongoDB, Firebase, Nasuni, BitSight, and other portfolio examples illustrate different aspects of that strategy, although individual deal sponsorship must be established separately.
In 2023, Hazard articulated a broader claim: AI would cease being a useful distinction between technology companies because AI capabilities would spread throughout the software economy.
Flybridge's January 2024 third-wave AI thesis formalized investment opportunities across AI-native enterprise applications, infrastructure, and developer platforms.
This was a strategic continuity rather than a complete abandonment of the firm's earlier playbook.
The models were new. The investment question remained familiar: which company would convert technical capability into a product customers adopted repeatedly and paid to operate?
Capital-allocation doctrine: Treat model capability as an enabling input. Look for the workflow integration, domain specificity, and distribution advantage that make the resulting business durable.
Applied AI: Beyond The AlgorithmsEverything Everywhere All at OnceFlybridge’s Third Wave of AI Investing
§ 05 · Blitzy and the Agentic Software Thesis
The Developer Becomes the Orchestrator
Blitzy offers a contemporary test of that doctrine.
The company was co-founded in 2023 by Brian Elliott, a former Army Ranger with experience in large-scale operational simulation, and Sid Pardeshi, a former NVIDIA engineer and inventor.
The founders met at Harvard. They built Blitzy around a problem that becomes more consequential as models improve: the difference between generating isolated code and understanding an entire enterprise software environment.
According to its investors, Blitzy's platform constructs a representation of an existing codebase, including its dependencies and architecture, and uses that context to coordinate specialized AI agents working on long-duration engineering tasks.
The product's commercial thesis is that enterprises need systems capable of handling complex software modernization, not just faster autocomplete.
Flybridge participated in Blitzy's investor network, which also includes Dave Blundin's Link Ventures.
Blitzy emerged from stealth with a reported $4.4 million seed financing in September 2024. In May 2026, Northzone led a $200 million financing at a reported $1.4 billion valuation, with continued participation from existing investors including Flybridge and Link Ventures.
Hazard also participated in a public conversation with Elliott and Pardeshi about autonomous software development:
The available evidence establishes a direct professional association and an institutional investment connection.
It does not establish that Hazard personally led Blitzy's seed investment, holds a Blitzy board seat, owns shares independently of Flybridge, or directly recruited the founders.
The Harvard/Flybridge relationship is relevant context, not proof that any one investor originated the transaction.
The Structural Continuity
MongoDB helped developers work around the limitations of traditional database procurement and deployment.
Blitzy attempts to remove a different constraint: the capacity of human engineering teams to understand and modify complex repositories at enterprise scale.
In both cases, developer productivity is the entry point.
But the comparison has a limit. MongoDB's success was demonstrated across many years of adoption and public-company operation. Blitzy's recent valuation is a financing event, not proof that autonomous software development has achieved equivalent economic durability.
The question: If models commoditize code generation, who owns the trusted operating layer that plans, coordinates, and validates software change?
The answer remains commercially open.
The Blundin Connection
Dave Blundin and Hazard operate within overlapping Boston-Cambridge investment networks.
Their respective investment organizations, Link Ventures and Flybridge, participated in Blitzy's financing ecosystem.
That is evidence of a shared investment network, not proof of a personal partnership, coordinated investment strategy, or shared limited-partner ownership.
The contrast between their models is revealing.
Blundin is associated with a venture-studio architecture that uses proprietary data and operating infrastructure to develop and select companies.
Hazard's record more clearly demonstrates institutional venture investing built around founder access, technology adoption patterns, and long-duration portfolio governance.
One model seeks to manufacture advantages before companies scale. The other seeks to recognize and finance scalable advantages early.
These are analytically distinct models that may coexist within the same venture syndicate.
Partnering with BlitzyBlitzy’s $200M financing at a $1.4B valuationBlitzy’s $4.4M seed financingHazard and the Blitzy founders — conversation
§ 06 · The Investor's Three Alphas
Recognition, Access, Conversion
In September 2026, Hazard published a reflection on what public-market investing frameworks miss about venture capital.
His central distinction is unusually useful.
An investor must do more than correctly evaluate an opportunity.
They must encounter the opportunity before it becomes broadly recognized, persuade the exceptional founder to accept their capital, and acquire an ownership position substantial enough for success to matter.
Hazard separated those requirements into three forms of advantage:
Recognition alpha: Identify exceptional people and opportunities before consensus forms.
Access alpha: Arrange for those opportunities to enter the investor's consideration set.
Conversion alpha: Persuade the founder to choose the investor and secure economically meaningful participation.
This framework reveals why his institutional activities should not be treated as biographical decoration.
The Boston-Cambridge network, Flybridge's investment partnerships, university relationships, specialized founder communities, and accumulated credibility from portfolio successes all potentially contribute to the second and third forms of advantage.
MongoDB provides an example of recognition validated by later market outcomes.
XFactor illustrates deliberate attention to access.
A firm's sustained relationships with successful founders can improve conversion, although individual transaction outcomes remain private.
The governing equation:
Great venture investing requires more than being right about technology. It requires being early enough to act, connected enough to see the opportunity, and valuable enough for the founder to choose the investor.
What VCs Can Learn From Public Investors… And What They Can’t
§ 07 · Narrative Tensions
What the Portfolio Cannot Prove
There are several limits to a compelling story about Hazard.
Attribution. Flybridge's historical investment successes cannot automatically be credited to Hazard personally. MongoDB has unusually clear board and investment evidence; other portfolio positions may involve different partners.
Survivorship. Successful exits and unicorn valuations are visible. Fund-level returns, ownership dilution, missed opportunities, failed investments, and opportunity costs are less transparent.
Technical foresight. Hazard's record supports sophisticated judgment about developer behavior and software economics. It does not establish that he personally predicted every important underlying technical invention.
Institutional advantage. University-linked deal flow may improve access, but selective observation of successful companies does not establish superior risk-adjusted returns.
Capital intensity. A preference for software and applied AI does not imply an absolute refusal to invest in businesses with physical infrastructure requirements. Bowery Farming, an AI-associated vertical farming investment, ceased operations in November 2024 and provides a useful counterexample to any overly neat account of portfolio success.
Valuation versus realization. Blitzy's reported $1.4 billion valuation is a private financing mark. It should not be counted as an investor exit or cash distribution.
Autonomy versus control. Hazard's September 2026 AI-safety commentary raises a tension for investors in increasingly autonomous software. The capacity to orchestrate many agents also increases the importance of authorization, containment, system-level validation, and operational security.
The strongest reading is therefore more restrained than a claim of technological clairvoyance.
Hazard has articulated a durable investment framework for detecting changes in enterprise software economics, while assembling institutions that expand access to founders positioned to exploit those changes.
The public record cannot yet establish the full ownership-adjusted returns of that system.
Why I’m Still an AI Optimist—and Still Think We Should PauseBowery Farming is ceasing operations
§ 08 · Option Space
Where the Architecture Points Next
The extension of Hazard's investment history into agentic AI suggests several possible future investment areas.
These are analytical projections, not claims about current undisclosed transactions:
- Enterprise systems that govern, secure, and validate autonomous agents.
- Persistent context and data infrastructure outside model context windows.
- Developer platforms that coordinate long-horizon AI workflows.
- Domain-specific AI applications with integration and distribution advantages.
- Infrastructure for evaluating agent reliability, permissions, and downstream business results.
Blitzy, MongoDB, and Flybridge's AI infrastructure investments provide a useful conceptual bridge between those opportunities.
The remaining question is whether AI changes the location of software purchasing authority once again.
If developers were the new buyers of infrastructure in the cloud era, the agentic era could produce a new selection mechanism: software chosen, evaluated, or operated by automated systems under human and institutional control.
That possibility is an inference, not a declared Hazard investment thesis.
The next infrastructure battle may be about who supplies the environment in which agents are permitted to act.
Flybridge’s Third Wave of AI InvestingPartnering with Blitzy
Chronology
Career Timeline
- Stanford UniversityBA with honors, Economics and Political Science.
- Bain & Company / Company Assistance LimitedEarly corporate strategy and investment experience.
- Harvard Business SchoolMBA, Baker Scholar and Ford Scholar.
- 1994Joins Greylock Partners.
- 2002Co-founds Flybridge Capital Partners.
- October 2009Joins MongoDB board; Flybridge backs the company.
- 2017MongoDB IPO; launch of XFactor Ventures.
- February 2019Publishes the Applied AI thesis emphasizing domain expertise and workflow integration.
- February 2023Argues that AI will become pervasive across software businesses.
- January 2024Flybridge articulates its third-wave AI investment thesis.
- September 2024Blitzy announces $4.4M seed financing.
- May 2026Blitzy announces $200M financing at a reported $1.4B valuation.
- September 2026Publishes reflections on venture-investor judgment and AI risk.
Relational Cartography
The Blitzy intersection
Flybridge and Link Ventures appear together in Northzone’s financing announcement. These links describe an institutional investment network. They do not establish Hazard’s personal deal sponsorship, a Blitzy board seat, or a personal partnership with Blundin.
- Dave Blundin
Link Ventures and Flybridge · institutional co-investment in Blitzy
- Brian Elliott
Blitzy co-founder and CEO · Flybridge portfolio relationship
- Sid Pardeshi
Blitzy co-founder and CTO · Flybridge portfolio relationship
- Flybridge — Investment TeamProfessional roles and university-linked ecosystem
- MongoDB — Board of DirectorsCurrent director; service since October 2009
- XFactor Ventures — Chip HazardEducation, Greylock chronology, and access initiative
- Reflections on MongoDB’s IPOChip Hazard · November 15, 2017
- Applied AI: Beyond The AlgorithmsChip Hazard · February 4, 2019
- Everything Everywhere All at OnceChip Hazard · February 9, 2023
- Flybridge’s Third Wave of AI InvestingFlybridge · January 11, 2024
- Partnering with BlitzyNorthzone · May 5, 2026 · financing and investor-described architecture
- Blitzy’s $200M financing at a $1.4B valuationNixon Peabody · June 4, 2026
- Blitzy’s $4.4M seed financingInfotechLead · September 16, 2024 · reported round size
- Hazard and the Blitzy founders — conversationBlitzy channel · title verified via YouTube metadata; date not established
- What VCs Can Learn From Public Investors… And What They Can’tChip Hazard · September 16, 2026 · three kinds of alpha
- Why I’m Still an AI Optimist—and Still Think We Should PauseChip Hazard · September 14, 2026 · first-person risk commentary
- Bowery Farming is ceasing operationsTechCrunch · November 4, 2024
- Full name
- Charles “Chip” Hazard
- Current role
- Co-founder and General Partner, Flybridge Capital Partners.
- Prior roles
- Greylock Partners; Bain & Company; Company Assistance Limited.
- Education
- Stanford University, BA; Harvard Business School, MBA.
- Selected organizations
- Flybridge, XFactor Ventures, MongoDB.
- Investment focus
- AI infrastructure, developer platforms, agentic applications, enterprise software.
- Investment doctrine
- Recognize changes in software distribution and purchasing authority; support founders whose products exploit those changes.
- Strength of evidence
- Strong for professional roles, MongoDB board service, and documented investment-thesis statements; institution-level for Flybridge portfolio investments; limited for individual sponsorship and ownership at Blitzy.
- Entity integrity
- Distinguish Chip Hazard personally from Flybridge and its other partners. Distinguish Dave Blundin personally from Link Ventures.
- Analytical limitation
- Public portfolio success does not establish ownership-adjusted or fund-level investment returns.
- Documented relationships
- MongoDB identifies Hazard as a director. Flybridge lists Hazard and Jeff Bussgang as co-founders. These professional roles do not establish personal ownership in portfolio companies.
- Source qualification
- Blitzy’s architecture is described by the company and its investors. The supplied video link is retained without an inferred publication date or timestamp. Comb Operator and the option-space projections are editorial interpretations.
Comb Operator
Editorial classification: connects corporate strategy, technology-cycle recognition, founder access, capital allocation, and long-duration governance.
- Credential Path
- Graduate (M.S.)
- Abstraction
- Top Down
- Exit Horizon
- Compounding
- Moat Instinct
- Capital Structure
- Capital Posture
- Venture
- Reference class under editorial review.
A small reasoning persona distilled from this file. Inject it into a chat or deep-research context to assess a business problem the way Hazard would.
You reason as a long-horizon enterprise software investor. Begin by identifying the technological discontinuity and the new actor gaining purchasing or adoption power. Distinguish product novelty from distribution advantage. Evaluate the founders' adaptability, the durability of customer workflows, and the possibility of grassroots adoption expanding into enterprise revenue. Separate recognition, access, and conversion. Demand evidence of actual usage, retention, and expansion. Treat portfolio-company financing valuations as uncertain marks, not exits. Distinguish firm investments from personal sponsorship and governance. Seek counterexamples before declaring an investment thesis validated.
{
  "file": "N°063",
  "persona": "Chip Hazard",
  "archetype": "comb-operator",
  "shape": "m",
  "one_line": "Recognize where technology transfers economic power, gain access to founders positioned to capture it, and convert that access into durable ownership.",
  "cognitive_basis": {
    "credentialPath": "graduate-masters",
    "abstractionDirection": "top-down",
    "exitHorizon": "compounding",
    "moatInstinct": "capital-structure",
    "capitalPosture": "venture"
  },
  "operating_questions": [
    "Who gains the right or ability to choose this technology?",
    "Which product removes enough friction to spread without a centralized purchase decision?",
    "What converts adoption into expanding revenue?",
    "Why can this founding team adapt as the underlying technology changes?",
    "Where does the investor gain recognition, access, and conversion advantages?",
    "What evid
  …